DELVE IN EXPLAINER | 02
Airtel Money might be the biggest London listing in recent years, but can it pull off the bigger challenge of turning millions of telecom subscribers into regular financial-services customers?
More than 75 million people across Airtel Money’s 13 African markets use Airtel’s telecom services but don’t use its mobile-money platform. By June 2026, Airtel Money had approximately 53 million monthly active users, representing 41% of the telecom subscriber base across those markets.
That gives Airtel a head start. But a customer who uses its network for calls and data won’t necessarily choose it for payments, savings or credit.
A SHORT HISTORY
Much of Airtel’s African network traces back to Celtel, founded by Mo Ibrahim. Kuwait’s MTC bought Celtel in 2005, later rebranding its operations Zain. Bharti Airtel acquired Zain’s operations in 15 African countries in 2010 and launched Airtel Money the following year. The telecom business provided the customer relationships and distribution on which mobile money could grow.
What will the IPO deliver?
On 1 October 2026, Airtel Money announced an offer price of £1.96 per share, valuing the business at approximately £5.3 billion ($7 billion), below the $8–9 billion valuation reportedly sought ahead of the listing. Admission to the London Stock Exchange is expected on 14 October.
Existing shareholders plan to sell £529 million ($702 million) worth of shares. The proceeds go to them, with no fresh funding raised for Airtel Money. Airtel Africa is expected to remain a long-term strategic shareholder.
The listing will give Airtel Money a separate stock-market value and provide a benchmark for assessing African mobile-money competitors such as M-Pesa and MTN’s MoMo.
For investors, the attraction is an established business with millions of potential customers already using its telecom parent’s network. The lower offer valuation makes the price more tempting, but does it leave enough room for the costs of winning those customers—and the risk that they choose another wallet?
Why Kenya counts
Kenya shows how deeply mobile money can become embedded in everyday life, and how difficult it can be to challenge an established provider.
At the end of June, Airtel Money held 11.1% of Kenya’s mobile-money subscriptions, against M-Pesa’s 88.8%, according to the Communications Authority of Kenya. Kenya is not among the six leading markets Airtel identifies: Uganda, Zambia, Tanzania, Malawi, the Democratic Republic of Congo and Gabon.
The opportunity extends well beyond winning customers from M-Pesa. Kenya offers a benchmark for deeper mobile-money adoption elsewhere, although each market has its own competitors and payment habits.
How could Airtel earn more from each customer?
A wage payment lands in the wallet. Does the customer withdraw it all as cash, or use it to pay the grocer, settle an electricity bill and send money home? Airtel wants more of that money to keep moving digitally.
The distinction matters for profitability. CEO Ian Ferrao told Semafor that payments and transfers generate better margins than cash deposits and withdrawals.
Growth therefore depends on attracting customers and giving them more reasons to transact. Services already extend to merchant and enterprise payments, with loans, savings, insurance and cards available in selected markets. The platform serves more than 3,700 enterprises, including governments, NGOs and businesses. Lending, savings and insurance currently account for only about 4% of the business.
For local businesses, wider adoption could mean more customers able to pay digitally and easier payments to staff and suppliers. Digital receipts could also help demonstrate creditworthiness: a recent World Bank Study across 101 economies found that firms receiving electronic payments were three percentage points less likely to be fully credit constrained. But the listing itself raises no fresh expansion capital: those benefits depend on Airtel extending useful, affordable services and businesses choosing to use them.
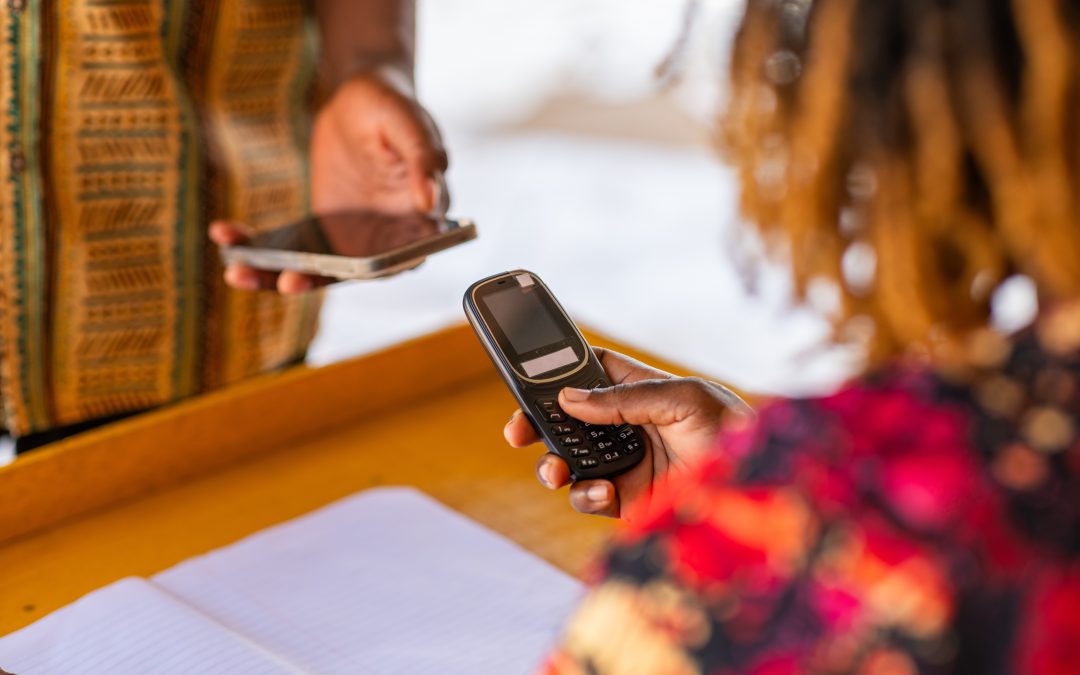
Smartphones could help deepen usage. Around half of Airtel Money customers have one, but only about 13% of those customers used its app over the twelve months to June. Basic-phone services remain essential for customers without affordable smartphones or reliable data access.
Steps to success
The 75 million untapped subscribers represent potential, rather than guaranteed customers. Airtel needs to understand why they haven’t adopted its wallet, as well as whether customers rely on cash or already use another provider.
Winning them over starts with an everyday need: receiving wages, paying a bill or sending money home. Competitive fees, reliable transactions and more shops accepting the wallet can then encourage repeat use. Customers also need confidence that a nearby agent can provide cash when required, and that they can send money to other networks and banks.
Investors will want that increased use to translate into sustained earnings. Currency movements can affect returns, while fraud and service failures can quickly undermine customer trust.
The IPO puts a price on Airtel Money. Its next task is to give those 75 million telecom subscribers a reason to use it—and keep using it.